Table of Contents
- HS code for PE stretch film (used with pallet wrappers)
- HS code for PE shrink film
- HS codes for related PE films
- Reference import duty on PE film
- VAT on imported PE film and a worked example
- Is PE film subject to environmental protection tax?
- Notes on declaring the PE film HS code to customs
- Buying PE film domestically - a simpler option
- Frequently asked questions
- Contact
- References
Reviewed and updated by ICD - Week 43/2026
PE pallet stretch film and PE shrink film in rolls are usually declared under HS code 3920.10.90. Under Decree 26/2023/ND-CP, the preferential (MFN) import duty for this line is 6%, the standard rate is 9%, and it can fall to 0% with a valid certificate of origin (C/O) under an FTA. Import VAT is 8% through 31 December 2026 under Decree 174/2025/ND-CP. The final code must be checked against the actual description of the shipment, or you can request an advance ruling for special consignments.
- PE stretch film, PE shrink film, and PE cling film in rolls: subheading 3920.10, with the 8-digit line commonly used being 3920.10.90
- Import duty on 3920.10.90: preferential 6%, standard 9%, 0% with a valid C/O under ATIGA, ACFTA, AKFTA; for other FTAs, check the schedule of each agreement
- VAT of 8% from 1 July 2025 through 31 December 2026, calculated on the taxable value plus import duty
- PE bags fall under 3923.21 (12-15%), not the same group as film; PE foam sheet and laminated film fall under heading 39.21
Companies importing PE stretch film or PE shrink film need the correct HS code to declare to customs, calculate import duty, and prepare the right C/O. This guide checks each code against the regulations in force as of October 2026, with document numbers and issue dates, so you can verify them yourself before opening a customs declaration.
HS code for PE stretch film (used with pallet wrappers)
PE stretch film (stretch wrap) used with turntable pallet wrappers falls under heading 39.20, subheading 3920.10. Heading 39.20 covers plates, sheets, film, foil, and strip of plastics, non-cellular and not reinforced, laminated, supported, or similarly combined with other materials; subheading 3920.10 covers products of polymers of ethylene, that is polyethylene (PE), including LDPE and LLDPE.
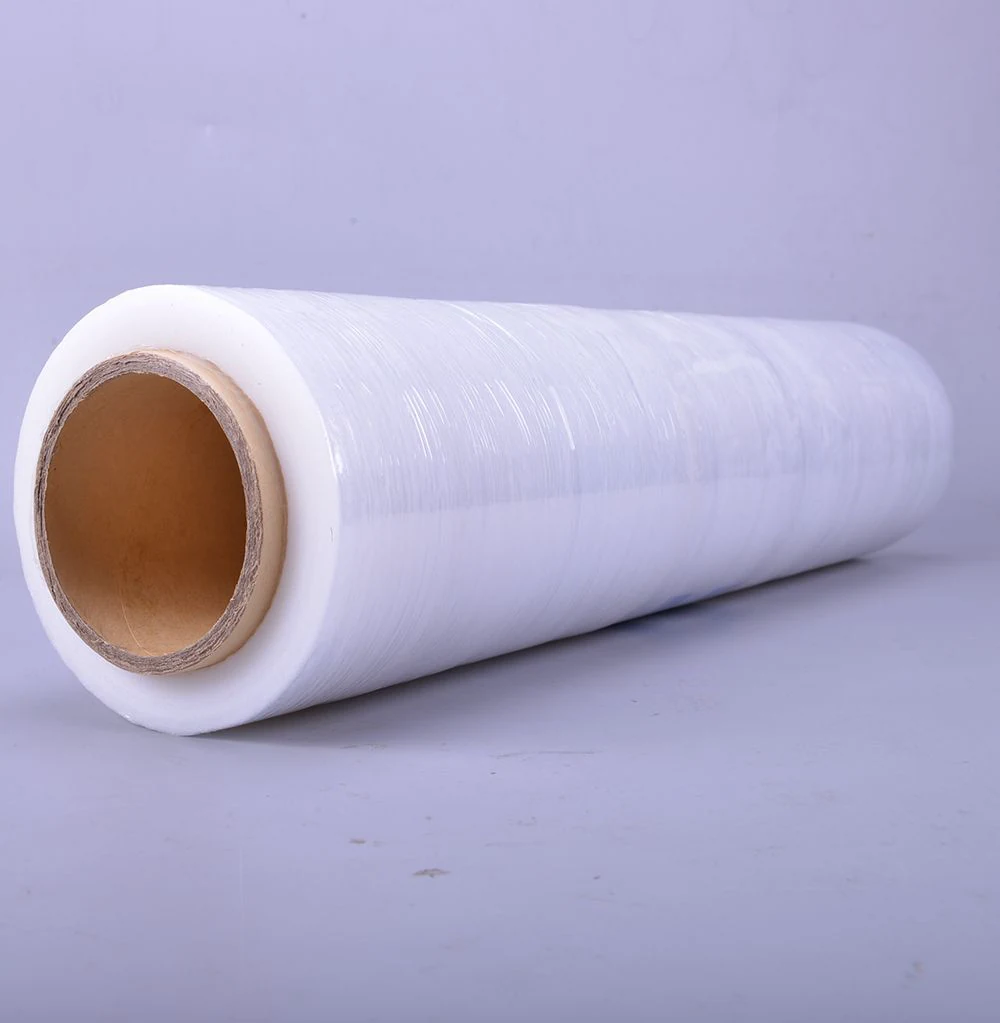
At the 8-digit level, the preferential import tariff issued with Decree 26/2023/ND-CP of 31 May 2023 (effective 15 July 2023) splits this subheading into three lines: 3920.10.11 for rigid plates and sheets, 3920.10.19 for other plates and sheets, and 3920.10.90 for other. Stretch film in thin, flexible rolls is neither plate nor sheet, so it falls under 3920.10.90. The tariff has no 3920.10.10 line, although some older articles still list one.
Commercial stretch wrap (500 mm x 7-23 kg rolls) matches this description. The 6-digit HS code is common to all countries under the World Customs Organization (WCO) Harmonized System; Vietnam’s 8-digit code is looked up in the List of Export and Import Goods issued with Circular 31/2022/TT-BTC of 8 June 2022.
| Level | Code | Description in the tariff | Preferential import duty |
|---|---|---|---|
| Heading | 39.20 | Other plates, sheets, film, foil, and strip of plastics, non-cellular, not reinforced, not laminated, not combined with other materials | Depends on the line |
| Subheading | 3920.10 | Of polymers of ethylene | Depends on the line |
| 8-digit line | 3920.10.11 | Plates and sheets, rigid | 6% |
| 8-digit line | 3920.10.19 | Plates and sheets, other | 6% |
| 8-digit line | 3920.10.90 | Other (including stretch film and shrink film in rolls) | 6% |
HS code for PE shrink film
PE shrink film also falls under subheading 3920.10, line 3920.10.90, because it is still non-cellular, unreinforced PE film; the HS code is not split by heat-shrink function. What separates the two is the technical description on the declaration, invoice, and packing list: write “shrink film” or “heat shrinkable film” for shrink film and “stretch film” for stretch film, together with the material, thickness, width, and roll form. A clear description avoids confusion when customs inspect the goods.
To tell the two types apart by use before ordering, see the article what is PE shrink film. PE cling film in rolls also falls under line 3920.10.90 if it is single-layer PE film; cling film made from PVC falls under subheading 3920.43 or 3920.49, depending on the plasticizer content.
| Film type | Use | Commonly used HS code | What to state on the declaration |
|---|---|---|---|
| PE stretch film | Wrapping pallets by hand or with a wrapper | 3920.10.90 | LLDPE/LDPE, thickness in microns, width, unprinted |
| PE shrink film | Heat-shrinking around bundles, bottles, cartons | 3920.10.90 | State heat shrinkable, thickness, width |
| PE cling film | Wrapping food, covering surfaces | 3920.10.90 | Single-layer PE; PVC types fall under other headings |
Printed PE film, foam film, laminated film, and PE bags are the four cases most often declared wrongly. Each falls under a different heading because of its construction, not because of its use.
Printed PE film: still falls under heading 39.20. Note 10 to Chapter 39 of the HS Nomenclature (WCO, 2022 edition) provides that the expression “plates, sheets, film, foil, and strip” applies also to goods that are printed or surface-worked. Single-layer, non-cellular PE film printed with a logo or label is therefore still declared under 3920.10.90, and no separate code is needed for printed film.
Multilayer PE film and laminated film: heading 39.20 covers only goods that are not reinforced, not laminated, and not combined with other materials. PE film laminated with paper, aluminum, or fabric, or with a reinforcing layer, falls outside this heading and is usually considered under heading 39.21 (subheading 3921.90, preferential duty 6%). Co-extruded multilayer film made entirely of plastic needs its specific construction checked; this is a case where you should request an advance ruling.
| Goods | HS code (8 digits) | Preferential import duty | Standard import duty |
|---|---|---|---|
| PE pallet stretch film, in rolls | 3920.10.90 | 6% | 9% |
| PE shrink film, in rolls | 3920.10.90 | 6% | 9% |
| PE cling film, single-layer | 3920.10.90 | 6% | 9% |
| PE film printed with a logo or label, single-layer, non-cellular | 3920.10.90 | 6% | 9% |
| Non-cellular PE plates and sheets (rigid / other) | 3920.10.11 / 3920.10.19 | 6% | 9% |
| PE film laminated with paper, aluminum, or fabric, or reinforced | 3921.90 (depending on the 8-digit line) | 6% | 9% |
| Cellular polyethylene (foam PE) plates, sheets, and film | 3921.19 (depending on the 8-digit line) | 6% | 9% |
| Bags and sacks of polymers of ethylene | 3923.21 (depending on the 8-digit line) | 12-15% | 18-22.5% |
PE foam film: falls under subheading 3921.19 (cellular, other plastics), not 3921.11 because 3921.11 is for polymers of styrene. Cellular polyethylene plates, sheets, and film are declared under the matching 8-digit line in subheading 3921.19, with a preferential duty of 6%.
PE packaging tubes (PE bags, PE tubes): bags and sacks of polymers of ethylene fall under 3923.21 (heading 39.23 covers articles for the conveyance or packing of goods), with a preferential duty of 12% or 15% depending on the 8-digit line. Heading 39.17 covers plastic tubes, pipes, and fittings for piping, not bags or packaging film.
The preferential duty is taken from Appendix II of Decree 26/2023/ND-CP; the standard duty equals 150% of the preferential duty under Decision 15/2023/QD-TTg of 31 May 2023. The rates in the table are the rates of the tariff line, before any FTA preference.
Reference import duty on PE film
For line 3920.10.90, import duty depends on whether the shipment has a valid certificate of origin (C/O). Without a C/O, goods from a country with most-favored-nation treatment pay 6%; goods from a country without this arrangement pay the standard rate of 9%. With a valid C/O, line 3920.10.90 falls to 0% under the ATIGA, ACFTA, and AKFTA schedules; for CPTPP, EVFTA, and RCEP, check each agreement’s schedule by country of origin.
| Case | Applicable document | Duty rate for 3920.10.90 in 2026 |
|---|---|---|
| No C/O, country with MFN treatment | Decree 26/2023/ND-CP of 31 May 2023 | 6% |
| Not covered by MFN | Decision 15/2023/QD-TTg of 31 May 2023 | 9% |
| C/O Form D (ATIGA), ASEAN country | Decree 126/2022/ND-CP of 30 December 2022 | 0% |
| C/O Form E (ACFTA), China | Decree 118/2022/ND-CP of 30 December 2022 | 0% |
| C/O Form AK (AKFTA), Korea | Decree 119/2022/ND-CP of 30 December 2022, amended by Decree 81/2024/ND-CP | 0% |
| C/O RCEP | Decree 129/2022/ND-CP of 30 December 2022 | Check the schedule by code and country of origin |
| CPTPP | Decree 115/2022/ND-CP of 30 December 2022 | Check the schedule by code and country of origin |
| EVFTA (EUR.1 or self-certification of origin) | Decree 116/2022/ND-CP of 30 December 2022 | Check the schedule by code and country of origin |
The FTA tariff schedules for 2022-2027 have year-by-year roadmaps and conditions specific to each agreement: the goods must meet the rules of origin, the exporting country must be a member currently applying the agreement, and the C/O must be the right form and on time. Miss one condition and the shipment goes back to 6% or 9%. Decree 26/2023/ND-CP has been amended several times. Decree 199/2025/ND-CP of 8 July 2025 adjusted only the plastic resin lines of headings 39.01 and 39.02 in Chapter 39, and did not change heading 39.20 for film; even so, you should still check the tariff as of the date you open the declaration.
VAT on imported PE film and a worked example
Import VAT on PE film is 8% through 31 December 2026. Decree 174/2025/ND-CP of 30 June 2025, issued under National Assembly Resolution 204/2025/QH15, cuts VAT from 10% to 8% for goods groups currently taxed at 10%, applied uniformly at import, production, and trading, except the groups in Appendices I and II (telecommunications, finance, real estate, metal products, mining, goods subject to special consumption tax). Plastic film of heading 39.20 is not among these excluded groups; from 1 January 2027 the rate returns to 10% unless an extension is issued.
Besides import duty, VAT is also payable on a tax base made up of the customs value (usually the CIF price) plus import duty. For a company that files under the credit method, VAT on imports can be claimed as input tax, so the real cost of the shipment is mainly the import duty.
| Case | Import duty | VAT 8% | Total tax payable |
|---|---|---|---|
| With valid C/O (0%) | VND 0 | 8% x 100,000,000 = VND 8,000,000 | VND 8,000,000 |
| No C/O, MFN 6% | VND 6,000,000 | 8% x 106,000,000 = VND 8,480,000 | VND 14,480,000 |
| Standard rate 9% | VND 9,000,000 | 8% x 109,000,000 = VND 8,720,000 | VND 17,720,000 |
The assumed taxable value in all three cases is VND 100,000,000.
The example only illustrates the calculation; the value is an assumed figure. It excludes customs fees, port charges, domestic transport, and customs broker costs, which depend on the port and the service provider.
Is PE film subject to environmental protection tax?
Pallet stretch film and shrink film in rolls are not subject to environmental protection tax, because the taxable item in this group is plastic bags. Under the Law on Environmental Protection Tax 57/2010/QH12 and Resolution 579/2018/UBTVQH14 (effective 1 January 2019), plastic bags are taxed at VND 50,000/kg. A plastic bag here means a bag or sack with an opening, a bottom, and walls, made from single HDPE, LDPE, or LLDPE film; pre-packaged goods packaging and bags that meet environmentally friendly criteria are outside this scope.
So if the imported shipment is PE bags (code 3923.21), the company must add this tax on top of the 12-15% import duty; rolls of stretch film and shrink film are not taxed this way.
Notes on declaring the PE film HS code to customs
Declaring the wrong HS code is the most common reason a PE film shipment is held at the port or has its duty reassessed. Before opening the declaration, prepare and check:
- A full goods description: material (LLDPE/LDPE), structure (single or multilayer), thickness (microns), width, roll form, and intended use.
- Separate heading 3920 from 3921: non-cellular, unreinforced, unlaminated film falls under 3920; laminated, reinforced, or cellular film falls under 3921.
- Certificate of origin (C/O): the right form under the agreement; without a valid C/O the 6% or 9% rate applies.
- Classification analysis results: for high-value shipments or special films, request an advance ruling to avoid disputes at clearance.
- Check the current tariff: check the schedule as of the declaration date, because FTA duties change on a yearly roadmap.
| Real-world situation | Heading likely to apply | What to do |
|---|---|---|
| Single-layer PE film roll, unprinted or printed with a logo | 3920.10 | Declare by technical description, with the manufacturer’s TDS |
| PE film laminated with paper, aluminum, or reinforced | 3921.90 | Request an advance ruling if the shipment is high in value |
| Cellular polyethylene plates and sheets | 3921.19 | State the cellular form, thickness, and density |
| Sewn or welded PE bags and sacks | 3923.21 | Add environmental protection tax for plastic bags |
The advance ruling is a procedure set out in Article 28 of the Customs Law 2014 (Law 54/2014/QH13): the company submits a file with a sample or technical documents to customs before clearance, and the ruling is used as the basis for declaring later shipments of the same kind of goods. It suits laminated film, multilayer film, or film with special additives, where the product name alone is not enough to settle the code.
Buying PE film domestically - a simpler option
For regular but small-volume needs, buying PE film from a domestic supplier such as ICD Vietnam spares a company from handling customs procedures, certificates of origin, or import duty calculation. The buyer receives a Vietnamese VAT invoice for tax credit and orders as needed without having to gather a full import consignment.
Under ICD Vietnam’s delivery policy, orders are processed within 1-2 working days; delivery inside Hanoi and Ho Chi Minh City takes 1-3 days, between regions 2-5 days, and other provinces 3-7 days. If you import yourself, the real time depends on the ship schedule, the port of arrival, and the clearance time of each shipment.
| Criteria | Importing yourself | Buying domestically |
|---|---|---|
| Customs procedures, C/O | Handle yourself or hire a customs broker | None |
| Import duty | 0%, 6%, or 9% depending on the C/O and the tariff line | None |
| VAT | 8% at import through 31 December 2026 | Vietnamese VAT invoice for tax credit |
| Delivery time | Depends on the ship schedule, port of arrival, and clearance | ICD: order processed in 1-2 days, delivery 1-7 days depending on region |
See the 2026 PE film price list to compare domestic prices with the total cost of importing. See how to choose the right PE film by machine specification and load type. A company that buys PE pallet stretch film domestically has no customs declaration procedures and no import duty.
Frequently asked questions
What is the HS code for PE pallet stretch film?
PE pallet stretch film is made from LLDPE/LDPE, in rolls, single-layer and non-cellular, and falls under subheading 3920.10, with the 8-digit line commonly used being 3920.10.90 under the tariff issued with Decree 26/2023/ND-CP. The final code must be checked against the actual shipment description or confirmed by an advance ruling.
What is the import duty on PE stretch film in 2026?
Line 3920.10.90 has a preferential import duty of 6% (Decree 26/2023/ND-CP), a standard duty of 9% (Decision 15/2023/QD-TTg), and 0% with a valid C/O under ATIGA, ACFTA, or AKFTA; for CPTPP, EVFTA, and RCEP, check each agreement’s schedule.
Does PE film fall under heading 3920 or 3921?
It depends on the film’s structure. Film that is non-cellular, unreinforced, and not laminated with other materials falls under heading 3920. Film laminated with paper, aluminum, or fabric, reinforced, or cellular falls under heading 3921. Confusing the two headings is a declaration error that leads to duty being reassessed.
| Criteria | Heading 39.20 | Heading 39.21 |
|---|---|---|
| Construction | Non-cellular, unreinforced, not laminated with other materials | Cellular, or reinforced, laminated, or combined with other materials |
| PE film examples | Stretch film, shrink film, single-layer cling film | PE film laminated with paper, aluminum, or fabric; foam PE |
| Preferential import duty | 6% (3920.10) | 6% |
Is imported PE film exempt from import duty?
It can qualify for the special preferential import duty of 0% if the shipment has a valid certificate of origin (C/O) under agreements such as ATIGA, ACFTA, and AKFTA (line 3920.10.90 is 0%); for CPTPP, EVFTA, and RCEP, check each agreement’s schedule. Without a valid C/O, the goods pay 6% or 9%, plus 8% VAT through 31 December 2026.
Is VAT on imported PE film 8% or 10%?
8% from 1 July 2025 through 31 December 2026 under Decree 174/2025/ND-CP, because plastic film is not among the groups excluded in Appendices I and II of the decree. From 1 January 2027 the rate returns to 10% unless an extension is issued.
| Document | Date | Content relevant to PE film |
|---|---|---|
| Decree 26/2023/ND-CP | Issued 31 May 2023, effective 15 July 2023 | Preferential import tariff: 3920.10.11, 3920.10.19, 3920.10.90 all 6% |
| Decree 199/2025/ND-CP | 8 July 2025 | Amends Appendix II, touching only plastic resin headings 39.01 and 39.02; does not change heading 39.20 for film |
| Decree 174/2025/ND-CP | 30 June 2025 | VAT of 8% from 1 July 2025 through 31 December 2026 |
| Resolution 579/2018/UBTVQH14 | Effective 1 January 2019 | Environmental protection tax on plastic bags, not applied to film rolls |
Does PE film printed with a logo need a different HS code?
No. Note 10 to Chapter 39 of the HS Nomenclature provides that printed or surface-worked plates, film, and foil still fall under heading 39.20 or 39.21. Single-layer PE film printed with a logo is still declared under 3920.10.90.
Contact
- ICD stretch wrappers and PE film: View ICD products
- Northern Vietnam: 0983 797 186 | 090 345 9186
- Southern Vietnam: 098 6784 186
- Email: Sales@icdvietnam.com.vn
- Quote: Request a quote
References
- Decree 26/2023/ND-CP of 31 May 2023 on the Export Tariff and Preferential Import Tariff, Government Gazette (Appendix II, Chapter 39).
- VAT reduction from 1 July 2025 through 31 December 2026 (Decree 174/2025/ND-CP), Vietnam Government News.
- Principles for classifying HS codes in the export and import tariff - World Customs Organization (WCO) - Harmonized System; Note 10 to Chapter 39, HS Nomenclature 2022.
- Decision 15/2023/QD-TTg of 31 May 2023 on standard import duty rates.
- Decrees 115, 116, 118, 119, 126, 129/2022/ND-CP of 30 December 2022 on the special preferential import tariffs for 2022-2027; Decree 81/2024/ND-CP (amending Decree 119/2022) and 199/2025/ND-CP (amending Appendix II of Decree 26/2023).
- Circular 31/2022/TT-BTC of 8 June 2022 issuing the List of Vietnam’s Export and Import Goods.
- Customs Law 54/2014/QH13, Article 28 (advance ruling); Resolution 579/2018/UBTVQH14 on the Environmental Protection Tax Schedule.